A parking budget fails in review for one of two reasons: the revenue line is a guess, or the ask has no story attached to it. Finance staff and council members rarely argue with a number that comes with a visible method. They argue with the number that appears from nowhere, usually the one that goes up. Whether your jurisdiction is already in FY2027 or is still drafting a calendar-2027 plan, the same discipline applies, and it starts with separating what you know from what you are assuming.
Start With the Revenue Baseline, Not the Target
Build the revenue forecast from actuals, by stream. Meter and pay-station receipts, garage transient, monthly permits, citations and fines, and any contract or lease income each behave differently, and a single blended growth percentage hides the stream that is quietly shrinking.
For each stream, pull at least the last full fiscal year plus year-to-date actuals, then state three things explicitly:
- Volume assumption: transactions, occupied permit count, or citations issued, with the reason for any change.
- Price assumption: the rate in effect on each date during the fiscal year, including any increase already approved.
- Collection assumption: the share of citations and payments you expect to actually collect, since issued is not the same as received.
Public budgets show how modest a defensible assumption can look. Frederick, Maryland’s proposed fiscal 2026 parking budget projected about $6.3 million in revenue, roughly 3.4 percent above the prior year’s estimate, and proposed raising a monthly garage permit only from $102 to $107. That is a small, specific change tied to a named product, which is easier to defend than a general promise of growth.
Treat One-Time Events as One-Time
Closures change baselines, and budgets should say so. Jefferson City, Missouri, reported that demolishing the Madison Street garage removed roughly $300,000 in annual parking revenue, and local reporting tied planned rate increases partly to replacing that loss. If a facility is closing, reopening, or under restoration during your fiscal year, model it as its own scenario, with a start date, rather than burying it in a flat percentage.
The same logic applies in reverse. A construction project that suppressed demand last year, or a one-year event surge, should not be extrapolated into the next. Flag it, normalize it, and show finance the adjusted baseline.
Rate Adjustments That Survive Review
Rate proposals pass when they are framed as a cost-recovery or demand-management decision rather than a revenue grab. Two framings work:
Cost recovery. Belleville, Ontario, approved as part of its 2026 budget an increase in on-street parking from $1.50 to $2 per hour and the daily rate from $12.50 to $16 effective April 1, 2026, citing the rising cost of operating, maintaining and managing municipal parking infrastructure. Whatever you think of the numbers, the stated rationale is one a council member can repeat to a constituent.
Demand management. If occupancy data supports it, tie the rate to a target. Baltimore’s parking scorecard, for example, sets a goal that a share of its demand-based meter blocks sit within a 75 to 85 percent occupancy range. A rate change justified by blocks sitting consistently above or below target is an operational decision, not a political one. If you do not currently collect occupancy data, say so in the budget narrative and request the counts or sensor funding rather than implying you have evidence you lack.
Whichever framing you use, include in the proposal:
- Current rate, proposed rate, and effective date.
- Expected volume response. A price rise usually reduces some demand, so the revenue effect is less than rate change times current volume. Use a conservative elasticity and show the assumption.
- A comparison with comparable local facilities, so the proposed rate is not an outlier.
- The mid-year effective date effect. A rate effective April 1 produces only a partial year of benefit.
Revenue forecasts built on a full year of a new rate that starts mid-year are one of the most common reasons a department misses its number.
Expenditure Assumptions Finance Will Check
On the cost side, the lines that get questioned are labor, contracted services, and utilities. Labor often moves with citywide wage agreements outside the department’s control; Detroit’s FY 2025-26 municipal parking budget analysis, for instance, noted a proposed 7 percent increase in General Fund salaries and wages. Use the figure from your own HR or finance office, not a national average.
For operations contracts, note escalator clauses and renewal dates. For equipment, separate warranty-covered from out-of-warranty maintenance. And for maintenance generally, report the trend: Jefferson City’s proposed public parking budget showed a $260,000 parking lot maintenance line when it moved operations to a contractor, a reminder that maintenance spending is rarely flat once deferred work comes due.
Capital Requests: Show the Failure Cost
A capital request reads as a want unless it states what happens without it. For each project, give:
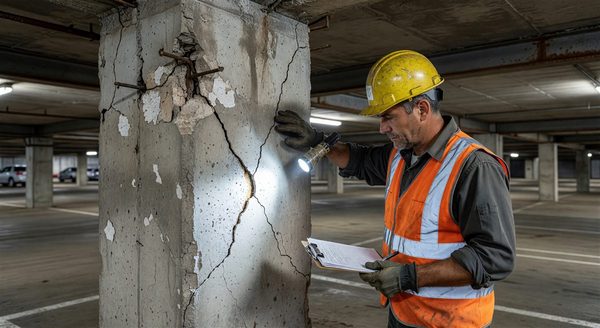
- Condition evidence: inspection reports, failure counts, repair spend over the past three years.
- Cost of inaction: rising repair cost, revenue lost to downtime, liability exposure, or code compliance.
- Options considered: repair, replace, or defer, with cost for each.
- Funding source and operating impact: whether the project is paid from parking fund reserves, bonds, or grants, and what it does to annual operating cost afterward.
Rank the requests. A budget with twelve unranked projects invites the reviewer to pick the ones to cut. A ranked list with a stated cutoff line puts the trade-off in your hands.
Close With the Reserve Position
End the narrative with the fund balance and the policy it is measured against. Many parking enterprise funds are expected to cover operating costs, debt service, and some capital replacement; show whether the proposed budget does that and by what margin. If your fund is a transfer contributor to a general fund, show that transfer explicitly as well.
The practical takeaway: before submission, give a finance analyst the workbook and ask them to find the assumption they cannot trace to a source. Fix that one, and the rest of the review gets shorter.